Shared Car Insurance Basics: The Protection Users Should Know
Car sharing lets users use a vehicle when needed, sparing them the burden of buying and maintaining a car, but the risks of driving the vehicle on the road remain. Insurance is an important way to bear these risks, yet the terms vary considerably between platforms. This article outlines the basic structure of car sharing insurance, common coverage, and situations that may not be covered, and explains how to handle an incident and what to look for when reading the terms, for your reference.
By: 車馳共享 Editorial Team Published About 8 min read
The Basic Structure of Car Sharing Insurance
Car sharing insurance is usually arranged by the vehicle owner or the operating platform, and during the rental period users generally become the beneficiaries or insured persons, though the exact arrangement depends on the service model. In general, the insurance includes basic components such as third-party liability, damage to or theft of the vehicle, and some platforms add personal accident cover. Users should check the insurer, the coverage period and the vehicles covered, and confirm that the rental time falls entirely within the coverage.
The insurance structure may also differ depending on the charging method. For example, for rentals charged by the hour or by the minute, the coverage period is usually tied to the start and end times of the booking. Some platforms summarise the insurance in the app, but the full policy terms prevail. If you have questions about the structure, check the relevant documents before renting rather than assuming every situation is covered.
In addition, the insurance arrangements for shared vehicles differ from ordinary private car insurance, because a vehicle may be driven alternately by several users. Insurers approve cover according to the driver requirements set by the platform, such as age and driving experience. Users need to confirm that they meet these eligibility requirements, otherwise even if a policy exists, they may face obstacles when making a claim. Understanding this basic structure is the starting point for evaluating any car sharing insurance.
Common Coverage
Car sharing insurance generally covers compensation for bodily injury and property damage to third parties, which is basic protection required by law in most regions. Damage to the vehicle itself, such as from collisions or scratches, and theft or deliberate vandalism of the vehicle are also commonly included. Some policies set an excess, meaning that even when insured, users must bear a certain amount of loss, so you should understand the level of the excess and how it is calculated before renting.
Some platforms offer extra options, such as add-on cover that reduces the excess, or roadside assistance in certain situations. These add-ons can make protection more complete, but they usually cost extra, so users should compare what they actually provide. On the other hand, personal medical or accident cover usually applies only to drivers and passengers, not to all pedestrians, so check who is covered and the maximum payout.
Because coverage varies by platform and region, users should not assume that all risks have been transferred simply because the vehicle is "insured". The specific description of coverage, the limits and the circumstances in which a claim can be made should be checked item by item in the policy. Listing these common items helps users quickly judge which risks are covered before renting, and which still require their own attention.
Situations That May Not Be Covered
Even with car sharing insurance, some situations are usually not covered, and users should know them in advance. For example, if the driver is under the influence of alcohol or drugs, does not hold a valid driving licence, or the accident results from breaking traffic laws, insurers generally refuse cover or make deductions. In addition, using the vehicle outside the designated area, lending it to an unregistered person, or using it for paid passenger transport may also exceed the conditions of the policy.
Some losses may also be excluded, such as loss of personal belongings in the car, normal wear and tear of tyres and the external body, or damage caused by intentional acts. If the accident occurs in a prohibited area or on a prohibited road listed in the policy, the claim may likewise be restricted. Users should pay particular attention to the "exclusions" section of the terms, as these often determine whether a claim can succeed, yet are easily overlooked when renting in a hurry.
Knowing what is not covered is therefore just as important as knowing what is. Before driving, users should review whether their conduct complies with the terms, for example whether they are driving as permitted and using the vehicle in line with the agreement. If in doubt, check with the platform or the insurer proactively, rather than discovering after the event that cover does not apply. Understanding these limits helps avoid unnecessary disputes and losses after an accident.
- Driver drunk or under the influence of drugs
- Driver does not hold a valid driving licence
- Vehicle used for purposes that breach the agreement, such as carrying passengers for profit
- Loss of or damage to personal belongings in the vehicle
- Losses caused by deliberate acts or breaches of traffic rules
Steps to take after an accident
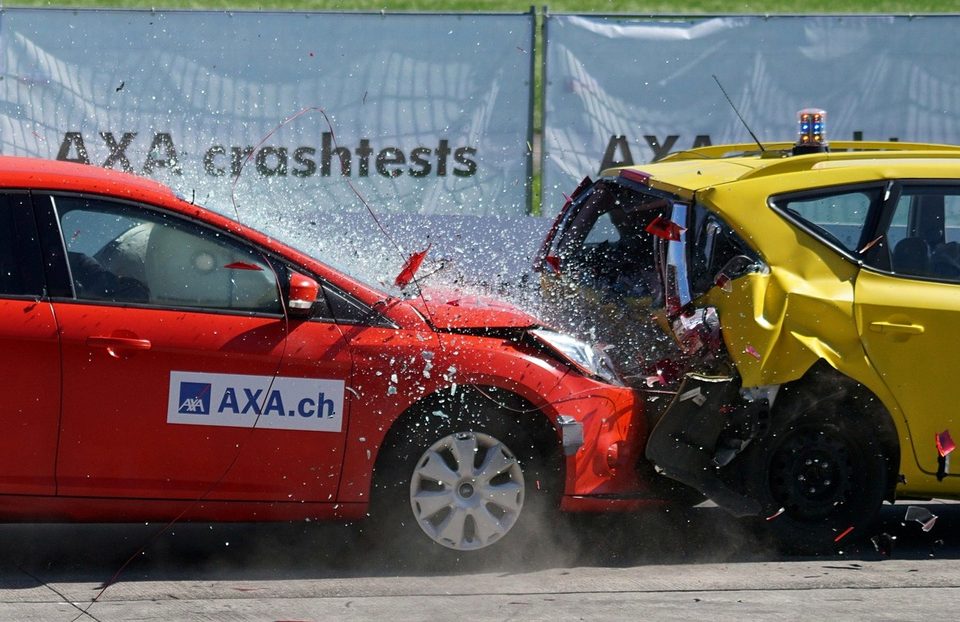
After an accident, first make sure everyone is safe, and call emergency services immediately if anyone is injured. Then, where possible, photograph the damage to the vehicle, the location of the incident, the surroundings and details of other vehicles involved, as these records often prove crucial when making a claim later. At the same time, follow the instructions in the app, notify the car sharing operator and complete the accident report as requested. Do not repair or move the vehicle without permission unless doing so is necessary to avoid further danger.
If a third party or property is affected, exchange identity and insurance details with the other party as far as possible, and keep photos of the scene and witnesses' contact details. If the police attend, describe what happened accurately and obtain the report reference number for follow-up. Some policies require written notice within a set time limit, so do not delay, as this could affect your right to claim. Throughout the process, staying calm and keeping accurate records helps clarify responsibility.
Afterwards, keep all relevant documents, including receipts, notices, report reference numbers and correspondence with the operator. If the outcome of a claim is not what you expected, first read the policy and the operator's claims explanation carefully, then consider enquiring with the insurer or lodging a complaint. If a dispute remains unresolved, seek independent mediation or legal advice. Following each step carefully makes the claims process far more orderly.
Key points when reading the insurance terms
When reading the car sharing insurance terms, first note when cover begins and ends, and confirm whether it covers the entire rental period, including a short time before the trip starts and after it ends. Next, check the compensation limits and excess amounts to understand how much you would actually have to pay in different situations. The sections on the insurer's rights are equally important, for example whether it may refuse payment or seek repayment in certain circumstances.
You should also pay close attention to the rules on driver eligibility, such as the minimum driving age, the length of time a licence has been held and the vehicle classes that may be driven. If you do not meet these requirements, cover may be reduced or cancelled. The definition of an "authorised driver" is also worth noting, as allowing an unauthorised person to drive usually falls under an exclusion. If you come across wording you do not understand while reading, ask the operator or insurer directly to avoid misunderstandings later.
Finally, compare the coverage of different plans rather than looking only at premium levels. Check whether add-on cover requires an extra fee, and whether certain protections apply only in particular areas or at particular times. If the terms are unclear, keep a written copy and confirm with the relevant body. Fully understanding the terms allows users to have a clear grasp of their rights and responsibilities before they set off.
How to reduce risk
The most important way to reduce risk is to become familiar with the vehicle's basic controls and safety features before renting, and to inspect the bodywork carefully for existing damage. If you find any problems, record them in the app immediately so you are not later mistakenly held responsible for them. Obeying traffic rules, keeping a safe following distance and avoiding fatigue or distraction while driving are all basic measures for reducing accidents.
Secondly, follow the requirements of the terms, for example by allowing only authorised persons to drive and making sure the driver continues to meet eligibility requirements. Never drive after drinking alcohol or taking medication that affects the mind, as such situations typically lead to cover being refused or reduced. At the end of the trip, park the vehicle in the designated location and make sure the doors are locked and no personal belongings have been left inside.
Finally, it is advisable to understand the scope of cover and claims arrangements before choosing a service, and to decide whether add-on protection is needed based on your own driving habits and purpose of use. Keeping an eye out for updates to the terms and notices from the operator regularly helps avoid misunderstandings caused by changes to the rules. Forming good usage habits not only reduces accidents but also makes your overall protection more secure and reliable.
- Inspect the bodywork before renting and record any existing damage in the app
- Allow only drivers authorised under the terms to drive the vehicle
- Obey traffic rules and avoid fatigue, distraction and drink driving
- Park the vehicle properly at the end of the trip and check it is locked and free of belongings
- Check regularly for updates to the terms and notices from the operator
Key Takeaways
-
Preparing before a claim After an accident, first ensure safety, then record as much of the scene as possible and notify the operator within the required time limit.
-
Key points of the terms Pay attention to when cover takes effect, compensation limits, excess amounts and driver eligibility rules, so that future claims are not hindered.
-
Ways to reduce risk Obeying traffic rules, allowing only authorised persons to drive and recording the vehicle's condition before and after renting are effective ways to reduce disputes.
This content is for general information only and does not constitute professional advice.